Indexed Life Insurance & Annuities
Your money should be doing more than sitting there.
I'm Christopher Momcilovich. Before insurance, I spent fifteen years as a band director, teaching kids to read something that looked impossible on paper. I do the same thing now with financial products most people have been sold at but never actually taught. Give me fifteen minutes and you'll understand how they work — then you decide what to do with that.
No cost, no obligation, no follow-up campaign. If it isn't a fit for you, I'll be the one to say so.
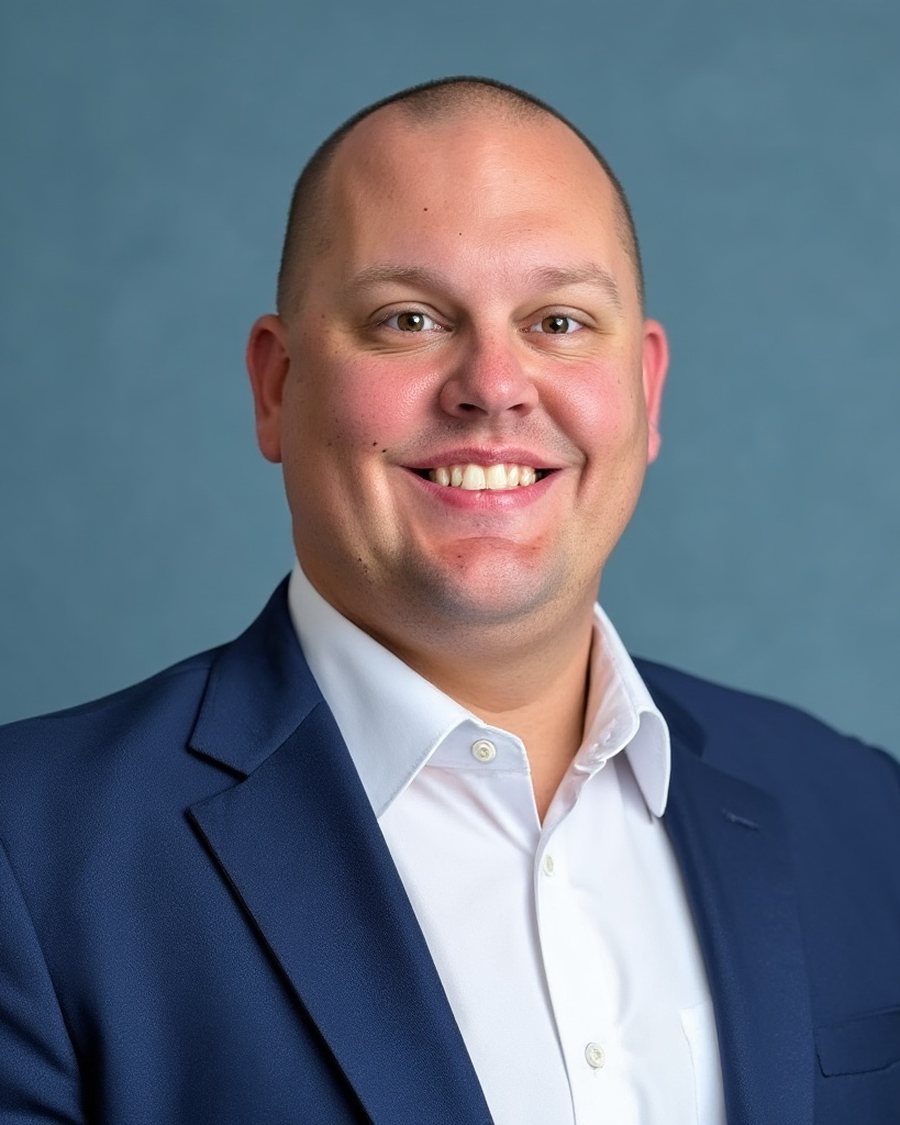
Licensed insurance agent·NPN 21364236·Independent — appointed with 20+ carriers·15 years in K–12 education·M.M.E., Bowling Green State University·Battle Creek
If you left a financial meeting nodding but not understanding, that wasn't your fault.
Caps. Participation rates. Riders. Surrender periods. Non-guaranteed illustrations. This industry has a vocabulary problem, and a lot of people in it are comfortable with that, because a confused person either signs or leaves quietly.
I taught fourteen-year-olds to sight-read. My entire job was taking something intimidating and making it obvious — and then checking whether it actually landed. That habit didn't go away when I changed careers.
How it works
What an indexed universal life policy actually is
In five sentences, without the brochure language.
There's a death benefit protecting your family from the day the policy is issued. That part is the foundation, not a bonus feature.
After the cost of the insurance, the remainder accumulates inside the policy.
Often the S&P 500. Linked to, not invested in — you don't own the shares.
In a year the index falls, your cash value isn't reduced by that market loss. In a year it soars, your credited growth is capped. You trade some of the upside for protection from the downside.
Those loans are generally not treated as taxable income when the policy is properly structured and stays in force.
What I'll also tell you
- This is not free money. There are insurance costs and policy fees, and they weigh heaviest in the early years.
- It's a long-term commitment. If there's a real chance you'd stop funding it in three years, it's the wrong tool — and I'd rather you hear that from me now.
- Illustrations show projected numbers that aren't guaranteed. I'll walk you through the guaranteed column too, because that's the column that matters if everything goes badly.
- If an employer match you're leaving on the table, or a credit card at 24%, would serve you better first — that's what I'll tell you to do first.
Three steps, and you can stop after any of them
Fifteen minutes on the phone
You tell me what you're working with and what you want your money to do. I ask questions. No presentation, no slides, no forms to fill out first.
Real numbers, your numbers
I run illustrations with actual carriers for your age, health and budget, and walk you through both the guaranteed and the projected columns so you can see the gap between them.
You decide, on your clock
Take it home. Show your spouse. Show your CPA. Sit on it for a month. There's no deadline coming from me, and no bonus period expiring Friday.
Who I sit down with
Teachers & school employees
I've worked in your building. I know what a pension statement looks like, and I know what most 403(b) lineups quietly cost you. If your retirement plan is one pension and a hope, that's a conversation worth having.
Business owners & 1099 earners
No employer match, no HR department, no benefits meeting in the fall — and a tax bill that grows with every good year. You need something you control.
Pre-retirees protecting what they've built
You've saved for decades and you're close enough now that a bad year actually matters. Annuities exist for exactly this problem, and they're worth understanding before you need them.
About
I got into this because I watched good people retire with less than they thought.
Fifteen-plus years as a K–12 band director across Michigan districts. A master's in music education from Bowling Green State. A community college ensemble I still conduct. Three kids, Battle Creek.
Somewhere in those years I sat through enough staff-room conversations about retirement to notice a pattern: smart, careful people who had never once had somebody sit down and explain their options without trying to sell them something in the same breath. I'd rather be the person who explains it. The selling takes care of itself when people actually understand what they're looking at.
Not everyone needs an IUL
Sometimes the right answer is an annuity that turns savings into income you can't outlive, or a term policy that pays off the house, or coverage so your children aren't handed a funeral bill. I write those too, and I'll point you at the simpler one when the simpler one is better.
Annuities·Mortgage protection·Final expense·Medicare supplement·Mortgage-free & debt-free strategies
Questions people actually ask
Is this an investment?
No, and I'll correct anyone who calls it one. It's a life insurance policy with a cash value component whose growth is linked to an index. It isn't a security, I'm not a registered investment advisor, and I'm not going to manage a portfolio for you.
How do you get paid?
By the insurance carrier, if and when a policy is issued. You never write me a check for my time. I'd rather you know that up front and weigh what I say accordingly.
What does the first call cost?
Nothing, and there's no version of it where you owe me something afterward. Fifteen minutes, mostly me asking questions.
Can you help me if I'm not local?
Almost always. Nearly all of my appointments are virtual, and between my own licensing and the agents I work alongside, we cover the country. If for some reason we can't help where you are, I'll tell you on the first call rather than waste your time.
Do we have to meet in person?
Only if you want to, and most people don't. Nearly everything I do is by phone or video. I meet in person around Battle Creek, Kalamazoo, and the surrounding communities.
Am I too old for this to make sense?
For an indexed policy, maybe — it depends on your age, your health and how long you'd be funding it. But "too old for an IUL" often means "right in the window for an annuity." I'd rather tell you honestly on a fifteen-minute call than have you wonder.
Let's have one honest conversation.
Fifteen minutes. You'll walk away understanding more than you did, whether or not you ever buy anything from me.
Would rather just talk? Call or text 269-341-1986. I answer my own phone.